5 Things to Not Ignore At a Home Showing

Don't ignore these at an open house

There are common things you should look for at a showing, like dripping faucets, but the less obvious things are sometimes revealing as well.

Looking at homes can be overwhelming, especially if it’s your first try at buying a place of your own. Most homes have some flaw, small or large, and sometimes you can pick up on them during a showing or an open house. While most problems can be corrected with enough money, time, and patience, being aware of these items will make the process – and your ownership – a lot easier.

Here are five things real estate agents say you should never ignore at a showing:

1. Clutter

Sometimes, clutter is just the end result of a busy life or too many things and not enough places to put them, but sometimes it’s covering up things you should really know about.

“Even though clutter is usually just clutter, it could be hiding some things,” says Laura Carroll Duckworth, a real estate agent with Flat Fee Redefined, an agency brokered by eXp Realty LLC in Springfield, Missouri. “I had one where the seller refused to move a lot of their stuff for the inspection, and then it turned out there was termite damage behind it.”

Termites are bad enough, but they’re not the only bugs you may come across living in a cluttered home. They’re all going to require an exterminator at minimum, and the problem could be a lot worse than you imagine.

“I was showing a foreclosure and they didn’t do a trash out of the property,” says Tammy Nevin, real estate agent with First Weber Inc. in Tomah, Wisconsin. “There was debris and garbage everywhere. It looked like they just picked up and walked out. The stench was a combination of cigarettes and cats. As I was walking through and I looked closer, I noticed lots of little bugs jumping around – they were fleas. We ran out of there pretty quickly.”

2. Room Deodorizers

Homeowners often will use plug-in deodorizers or other air fresheners to make their home smell welcoming to a potential buyer. But if you smell something more than just the air freshener, it’s time to look a little closer.

“Some people have air fresheners and room sprays and the buyer might wonder, ‘Oh, what are they trying to cover up?’” says Duckworth. “Sometimes they’re not trying to cover up anything, they just want the house to smell good for the buyers. Other times, there are layers to that scent that might indicate problems with mold, rodents or insects.”

3. Area Rugs

While it might not occur to you that a seller could be hiding damage in plain sight, it’s not uncommon. Area rugs should always be considered suspicious until you’ve seen what’s underneath.

“One of my clients purchased a home about seven years ago and it had beautiful hand-scraped hardwood floors throughout,” says Neil Brooks, real estate agent with My Home Group in Scottsdale, Arizona, and an agent within the Veterans United Realty Network. “During the showing, the owner was there and took us on a tour. When shown the living room, he pointed out the area rug and mentioned that it was expensive and placed it there so their grandchildren could play comfortably. He added that he would leave it for my client because it fits nicely in the room.

“My client decided to purchase the home, and upon moving in, moved the carpet to buff the floors to find out that the rug covered a three-foot area where the previous owners’ dog chewed the floor down, exposing the slab.”

4. The Neighborhood

Most neighborhoods show well enough during the daytime when everyone is at work. It still pays to familiarize yourself with the neighborhood you’re considering, especially if a house is having trouble selling.

“One major red flag is not the house itself, it’s the neighbors,” says Bob Thompson, a real estate agent with American Homes Of Eastern VA, Inc., in Hampton Roads, Virginia. “I encourage all my buyers to do what I call the Friday night drive-by. Every neighborhood looks great at 3 p.m. on a Tuesday, but weekends are when you find out what people are really like. That’s important because no one wants to get stuck next to the loud drunk neighbors or racist neighbors.”

5. DIY Repairs

Homeowners often do home repairs, and to a high quality standard, because they care about their homes and want to take care of them to the best of their ability. But sometimes, no matter how hard someone may try, they might just not be cut out for DIY. When those repairs are obvious, it’s something to pay close attention to.

“When you can tell the homeowner did their own repair work on something and did a poor job on it, that’s important – what else did they attempt to repair?” says Thompson. “Also be sure to look at minor repairs on a rehabbed property. If they did poor work on the small things, did they do poor work on the big things?”

What if You Spot a Problem at the Showing?

A showing is just a chance to get to know a house that you might be interested in. It’s an opportunity to see all the home’s visible red flags and decide how much those things bother you. This is why it’s so important not to get too serious about a house right away, even if you think it’s your dream home.

“Try not to fall in love with a home initially, just date it until you have a thorough understanding of what you’re buying,” says Brooks. “It’s a Realtor’s duty to be the voice of reason and point out all of the potential issues and err on the side of caution in order to protect their client.”

Once you’ve identified the issues that may or may not be serious enough to fall out of love with a property, it’s time to put pencil to paper. Ignoring issues won’t solve them, but every problem related to a home can be fixed, if you go in with your eyes open.

“Every issue can be overcome with time, money, expertise or a combination of all three,” says Aimee Thayer-Garcia, broker-associate at Montalvo Homes & Estates in Santa Cruz, California. “Ignoring red flags at a showing can set buyer, seller, and their agents up for a challenging escrow. Every transaction has its own speed bumps – a huge part of the work as an agent for buyer clients is preparing for them and setting expectations.”

Source: realestate.usnews.com ~ By: Kristi Waterworth ~ Image: Canva Pro

Escrow: What Is It And How Does It Work?

Escrow: What Is It And How Does It Work?

If you’re buying a home, you’ll probably hear the word “escrow” used in a few different contexts. Let’s look at what escrow is, how it works and how it can benefit you as a home buyer, seller or homeowner.

What Is Escrow?

Escrow is a legal arrangement in which a third party temporarily holds money or property until a particular condition has been met – such as the fulfillment of a purchase agreement.

How Does Escrow Work?

It’s used in real estate transactions to protect both the buyer and the seller during the home buying process. Throughout the term of the mortgage, an escrow account will hold funds for taxes and homeowners insurance.

What Is An Escrow Account?

In real estate, escrow is typically used for two reasons:

  • To protect the buyer’s good faith deposit, so the money goes to the right party according to the conditions of the sale
  • To hold a homeowner’s funds for property taxes and homeowners insurance.

Because of the different purposes served, there are two types of escrow accounts. One is used during the home buying process, while the other is used throughout the life of your loan.

Escrow Accounts For Home Buying

When you’re buying a home, your purchase agreement will usually include a good faith deposit – (also known as earnest money). This deposit shows the seller that you’re serious about purchasing the home. If the contract falls through due to the fault of the buyer, the seller usually gets to keep the money. If the home purchase is successful, the deposit will be applied to the buyer’s down payment.

To protect both the buyer and the seller, an escrow account will be set up to hold the deposit. The good faith deposit will sit in the escrow account until the transaction closes.

Sometimes, funds are held in another type of escrow account past the completion of the sale of the home. This is called an escrow holdback. There are many reasons an escrow holdback may be needed. For example, perhaps you agreed that the seller can stay in the home an extra month, or there are outstanding bills on the home that the seller is responsible for (a water bill, for example).

If you’re building a new home, money may remain in escrow until you’ve signed off on all the work. Once the conditions are met, the money will be released to the right party.

Escrow Accounts For Taxes And Insurance

After you purchase a home, your mortgage lender will establish an escrow account to pay for your taxes and homeowners insurance. Each month, your mortgage servicer takes a portion of your monthly mortgage payment and holds it in the escrow account until your tax and insurance payments are due.

The amount required for escrow is a moving target because your tax bill and insurance premiums can change from year to year. Your servicer will determine your escrow payments for the next year based on what bills they paid the previous year. To ensure there’s enough cash in escrow, most lenders require a minimum of 2 months’ worth of extra payments to be held in your account.

Your lender or servicer will analyze your escrow account annually to make sure they’re not collecting too much or too little. If their analysis of your escrow account determines that they’ve collected too much money for taxes and insurance, they’ll give you what’s called an escrow refund.

If their analysis shows they’ve collected too little, you’ll need to cover the difference. You may be given options to make a one-time payment or increase the amount of your monthly mortgage payment to make up for a shortage in your escrow account.

Who Manages An Escrow Account?

Escrow accounts may be handled by a variety of third parties, including an escrow company, escrow agent or mortgage servicer. Where you are in the process will determine who manages the account.

Escrow Companies And Escrow Agents

When you’re buying a home, escrow may be managed by a mortgage servicing company or agent. The escrow agent or company is sometimes the same as the title company.

The escrow company not only manages the buyer’s deposit, but they may also be responsible for holding the deed and other documents related to the sale of the home.

Because the escrow company is working for both the buyer and the seller in the real estate transaction, the fee for their services is usually split evenly between the two parties.

Mortgage Servicers

Your mortgage servicer manages your mortgage, from closing until you pay off your loan. Mortgage servicers are responsible for collecting your mortgage payment, maintaining the records of payments and managing your escrow account.

Your mortgage servicer is sometimes your originating lender – but not always. Sometimes, lenders sell the servicing rights to your loan. It’s a good idea to know ahead of time whether your lender typically services their own loans. Not all mortgage servicers provide the same level of service.

With your mortgage servicer taking care of your escrow account, you don’t have to worry about your tax or insurance bills – your servicer will make sure they know who to pay, and when.

The only exception is if you change insurance providers or policies. You will need to provide the new policy information to your servicer.

The Benefits Of An Escrow Account

The biggest benefit of having a Rocket Mortgage® escrow account is that you’ll have peace of mind knowing you’re being taken care of by the most awarded mortgage company ever, based on J.D. Power’s consumer surveys.*

For Home Buyers

An escrow account is key to protecting your deposit during a home sale. For example, say you have a purchase agreement, but the sale falls through due to a problem found during the home inspection.

If you’d given your deposit directly to the seller, there’s a chance they wouldn’t return your deposit. But since the deposit is being held by a third party, you can be confident it will be returned according to your agreement.

For Homeowners

An escrow account takes the pressure off you to come up with a lump sum to cover taxes and insurance. Since you’re paying for your taxes and insurance throughout the year, the payments are much more manageable.

Another bonus is that you don’t have to keep track of all the different due dates. When your tax bills and insurance premiums are due, your mortgage servicer will make sure those bills are paid on time, every time. That way, you’re not responsible for any late payments. Your servicer will even cover bills for you if your escrow account is short on funds – but, as mentioned above, you’ll be responsible for making up the shortage later.

For Lenders

Lenders have a vested interest in making sure your property taxes and insurance get paid:

  • If your tax bills don’t get paid, the tax authority could put a lien on your home – which could end up costing the lender money if the tax authority chooses to foreclose.
  • If your homeowners insurance coverage lapses, significant damage to or loss of the home could lead to extreme loss of value of the home.

Having an escrow account on the loan allows the lender to ensure the bills get paid.

The Disadvantages Of An Escrow Account

Although there really aren’t any disadvantages of having a mortgage escrow account, here are some that could be considered as such:

Higher Monthly Mortgage Payments

As stated before, an escrow account is funded through your monthly mortgage payment, making your monthly bill higher than it would be without escrow. But this also means that you don’t have to pay your taxes or insurance in a lump sum when they are due, so this is hardly a disadvantage when you think about it.

Lower Escrow Estimates Than Actually Required

Again, the amount needed for your escrow depends on your property taxes and homeowners insurance costs, which can change from year to year. Your servicer will determine the amount needed based on the previous year’s bills. But here’s the thing: When you first move into your home, your property is reassessed for tax purposes. This may cause your property taxes to increase substantially, especially if the home value has risen. When a servicer estimates the escrow, they may not be able to predict an increase in your property taxes.

Because of this, your escrow may come up short. If that happens, you’ll have to pay the difference with an increase in your monthly escrow payment. On the flip side, if there’s any money left over in your escrow after paying the taxes and insurance for the year, your servicer will refund you the excess funds.

Changes To Your Monthly Payment

Escrow is reassessed each year and, depending on if you were short or had excess money, your servicer will come up with a new estimate for the year. If you’re short, your mortgage payment will go up because the estimate will increase. This higher estimate is an effort to prevent another shortage. If you had too much money in the account, your mortgage payment may go down and you’ll receive a refund each year.

What Escrow Accounts Don’t Cover

Escrow accounts don’t cover all the expenses related to homeownership. Your lender or servicer won’t collect money to pay your utility bills or homeowners association (HOA) fees, for instance.

Supplemental tax bills also aren’t covered by escrow accounts. These are one-time tax bills that are issued due to a change in ownership or new construction.

Do You Need An Escrow Account?

It may be possible to pay for property taxes and insurance yourself instead of using an escrow account. Doing so will lower your monthly mortgage payment, but you’ll have to save for tax and insurance payments on your own. Plus, you may incur a fee for managing your own taxes and insurance. And because managing escrow accounts is a free service provided by servicers such as Rocket Mortgage, it doesn’t make financial sense to opt out of escrow for your mortgage.

Truthfully, not everyone even has an option for opting out of an escrow account on their loan. Escrow accounts are a requirement on certain loans. For VA loans, for example, you’ll need 10% down and a strong credit profile to opt out of having an escrow account. For conventional loans, you’ll need to have a down payment of 20% or more. FHA loans require all borrowers to have an escrow account.

It’s also possible to use your escrow account for some expenses and not others. Sometimes, lenders require escrow for property taxes but not homeowners insurance.

Source: rocketmortgage.com ~ By: VICTORIA ARAJ ~ Image: Canva Pro

How to Price Your Home to Sell

pricing your home for sale

Pricing your house to sell requires a “Goldilocks” frame of mind. A price that’s “just right” is the one that attracts a buyer, is in line with the market, and puts the most money in your pocket.

It took Goldilocks some time to find exactly what worked for her, but you might not have that luxury when selling your house. So here are some do’s and don’ts for pricing your home to sell.

Don’t price it too high

When selling a home, first impressions matter. Your house’s market debut is your first chance to attract a buyer and it’s important to get the pricing right. If your home is overpriced, you run the risk of buyers not seeing the listing.

Let’s say you want $299,000 for your home, but you list it at $315,000 to see if anyone will pay the higher price. A buyer with a budget of $299,000 may search online only for homes priced through $300,000. Because of the way it’s priced, your home won’t appear in any of those searches, and you could miss out on a potential buyer.

Don’t price it too low

Listing a home below its market value is a strategy some sellers use to generate interest in the property and possibly spark a bidding war. It’s also used by sellers who need to sell their property quickly.

But price your house too low and you could end up leaving some serious money on the table. A bargain-basement price could also turn some buyers away, as they may wonder if there are any underlying problems with the house.

Do consider the comps

Comparable sales or “comps” are recently sold homes that are similar to yours in size, location, and features. Armed with comps, your listing agent can put together a comprehensive report called a comparative market analysis, or CMA. A CMA can help you determine a realistic listing price.

“One of the challenges we have as a seller’s agent is to really pull back the curtain and show data,” says Michael J. Franco, a licensed associate real estate broker at Compass in New York City. “You have to prove to the seller that their place isn’t really different unless it really is unique, then it deserves a premium.”

Don’t overvalue your home’s upgrades

Spending $70,000 to renovate your kitchen and install a swimming pool means you can add $70,000 to your home’s selling price, right? Not always.

While some renovations may increase your home’s value, it’s unlikely you’ll get back the full dollar amount that you put in. Before investing in any improvements, look at comparable homes for sale near you to see if upgrades are in line with the neighborhood and if they appear to have an impact on resale value.

Don’t let your emotions get the best of you

Market research should be your guide when pricing a home to sell, not your emotions. A buyer doesn’t care what you paid for the house, the sweat equity you’ve put into the property, the years of memories you’ve created in the home, or how much profit you hope for.

“You have to separate yourself emotionally from the property,” Franco says. “Yes, hold on to your memories and the experiences you’ve had in the home. But when you’re selling, you have to focus on it as a business transaction. Chances are, it’s your biggest asset and you have to do what’s right.”

Do adjust the price or approach as needed

If, despite your efforts to identify the “just right” price, your home isn’t attracting offers, regroup with your agent as soon as possible. Try to figure out why your home isn’t selling and be open to making adjustments that will fix the problem.

Pricing: While it’s unlikely in a hot market, if your home is languishing without an offer, it may be necessary to drop the price. Perhaps the market has changed since your agent conducted the CMA. Take a look at some more comparable properties and adjust accordingly.

Marketing: Make sure there aren’t any errors in your listing. Confirm with your agent that the home is being shown in all of the appropriate places. Your agent may need to boost marketing efforts to increase the number of people who see your listing, like offering more open houses or posting 3D tours on social media.

Alternate ways to sell: If your home isn’t attracting a traditional buyer, you may have to look into other options, like selling to an iBuyer. An iBuyer is a real estate company that uses technology to buy homes with cash. While the process is typically faster and you don’t have to get your house ready to sell, iBuyers don’t operate in every market and you may need to have a specific style of home to qualify.

Condition: Talk with your agent about what improvements may improve the salability of your home, including necessary repairs, staging, or curb appeal upgrades. A little TLC can go a long way.

Thinking of Selling? You Want an Agent with These Skills

Selling your Home

Selling your house is a big decision. Your home is one of the biggest investments you’ve probably ever made, and it’s a place where you’ve created countless memories. That combo means there’s going to be a lot of emotions involved. You want someone who understands your perspective, knows what it feels like, and is an expert at helping homeowners just like you navigate the process of selling a home.

That’s where a good listing agent, also known as a seller’s agent, comes in. Here are just a few skills you’ll want your agent to have.

The Ability To Turn Something Complex into Something Simple

Some agents are going to use big, fancy real estate terms to try and impress you. But you shouldn’t have to know all the industry jargon in order to understand what they’re saying. If anything, it’s an agent’s job to keep it simple, so you don’t get overwhelmed or confused.

A great agent is going to be someone who is very good at explaining what’s happening in the housing market in a way that’s easy to understand. But they’ll take it one step further than that. They’ll explain what’s going on and, specifically, what that means for you. That way you’re always in the loop and it’s a lot easier to feel confident when you’re making a big decision. As Business Insider explains:

“Maybe you have a better rapport with one of the agents you’re considering, or you just feel like they’re easier to approach. You’re going to be working closely with this person, so it’s important to choose an agent you’re comfortable with.”

A Data-Based Approach on How To Price Your House

While it may be tempting to pick the agent who suggests the highest asking price for your house, that strategy may cost you. It’s easy to get caught up in the excitement when you see a bigger number, but overpricing your house can have consequences. It could mean your house will sit on the market longer because the higher price is actually turning away buyers.

Instead, partner with an agent who’s going to have an open conversation about how they recommend you should price your house. They won’t throw out a number just to win your listing. A great agent will back up their number with solid data, explain their pricing strategy, and make sure you’re both on the same page. As NerdWallet explains:

“An agent who recommends the highest price isn’t always the best choice. Choose an agent who backs up the recommendation with market knowledge.”

A Fair, but Objective Negotiator

The home-selling process can be emotional, especially if you’ve been in your house for a long time. But that sentimental tie can make it harder to be objective during negotiations. That’s where a trusted professional can really make a difference.

They’re skilled negotiators who know how to stay calm under pressure. You can count on them to handle the back-and-forth and have your best interests at heart throughout the process. Not to mention, they’ll be able to rely on their market expertise and what they’re seeing work in other transactions to offer the best advice possible. As Rocket Mortgage explains:

“Whether this is your first or third time selling a house, listing agents work to help make the home selling process smoother and less stressful. These real estate professionals know the ins and outs of the industry and can help you secure the best deal.”

Bottom Line

Whether you’re a first-time seller or you’ve been through this before, a great listing agent is the key to your success.  Feel free to connect with me. I am a skilled local expert and I will be with you through every step of the process.

Source: keepingcurrentmatters.com ~ Image: Canva pro

Negotiation Process of Selling a Home

Selling a Home

The negotiation process can be one of the most exciting parts of selling a home, but until you get there, you may be wringing your hands, worried that you won’t be able to secure the deal. Will you be deluged with offers, or will your home be pervaded by the lulling but ever-so-unnerving sound of crickets?

And if you do get just one or two offers, and they’re not as high as you’d hoped, what do you do?

Here’s how to navigate the real estate negotiation process and come to a deal that will make you happy. More than happy, even.

Getting those offers in

If you’re not in a rush to sell your house, it may make sense to see what offers roll in over a few months. But if you need to sell quickly (or just don’t want to wait), your real estate agent (here’s how to find a real estate agent in your area) might be able to push things along by setting a deadline—usually within a week or two of listing.

“When you expect multiple offers because your price is competitive or your home is in a popular neighborhood, you should always set a deadline,” says Cathy Baumbusch, a real estate agent with Re/Max Executives in Arlington, VA.

But you’ll need to be confident that your home is priced right, relative to its appeal. If all goes well, you can sell for over asking.

The negotiation process begins

Once you have an offer in hand, you’re probably scanning for one thing: the price.

“In our area, houses rarely sell for less than 90% to 95% of the asking price,” Baumbusch says. The offers on your home may fall in that range, but don’t rely on price alone. According to Baumbusch, every offer has five important components:

    • Price
    • Closing assistance
    • Closing date
    • Buyer financing
    • Contingencies

Some offers may seem great on the surface, but significantly less so once you dig in. For instance: Is the buyer asking for closing assistance? Often first-time buyers don’t have enough money to cover the down payment and the closing costs, so they’ll ask the seller to foot some of the bill—about 2% to 3% of the total closing costs is a common request. If you agree, any assistance you give will lower your bottom line, so factor this amount into the asking price.

The buyer’s time frame to close may not seem like a big deal on the surface, but it can actually matter a lot, especially if you give the buyer a long leash. If the deal falls through, you’ll have to put the house back on the market and wait for more offers. On the other hand, if the buyer wants to move in right away, you might be left scrambling (and, quite possibly, temporarily homeless). Make sure the timing works for you.

Good so far? Now make sure the buyer has financing. Hopefully, the buyer’s agent included a note verifying the buyer’s financing and how much the buyer will put toward the down payment and earnest money. The last thing you want is to accept an offer, only to find out afterward that the buyer can’t come up with the necessary cash.

Finally, look over contingencies, which give the buyer the option to back out of the deal if something goes wrong. The buyer may say the final sale is contingent on a home inspection, or he may want to move in early. Both requests are fairly standard and acceptable. But keep an eye out for buyers asking for too much. For example, “it would be over the line for a buyer to ask a seller to wait more than 30 to 60 days for the property to go under contract,” Baumbusch says.

When to counteroffer

The negotiation process doesn’t end here. You always have the option to return the buyer’s offer with a counteroffer of your own.

“You should always counter if the price is not what you are looking for, or if you can’t support the amount of closing cost help they are looking for,” Baumbusch says. But if you do, keep it reasonable. If the buyer was 15% below asking, he probably won’t go up to full asking amount. Consider being flexible with your price; you can always make it up in other ways. For example, submitting a counter with a slightly higher price and contingencies that may help you—like having the buyer waive an inspection to speed things along—might pay off in the end.

If you don’t agree with the buyer’s contingencies, consider your position first before making the next step in the negotiation process.

“If your home is in a popular area, [you] have an advantage,” Baumbusch says. Keep in mind, the buyer may not accept your counter outright. You can play “Let’s Make a Deal,” but always consider your bottom line.

Is it worth it to keep countering for a small amount of money or single contingency?

Don’t get trapped in a loop; consider the buyer’s side of things. These prospective buyers may be maxed out. To help you decide, ask your listing agent to call the buyer’s agent and hash it out it with them. Get some insight into the buyer’s state of mind, and whether they can budge.

Source: realtor.com ~ Image: Canva Pro

Should I Wait for Mortgage Rates To Come Down Before I Move?

Should I Wait for Mortgage Rates To Come Down Before I Move?

If you’ve got a move on your mind, you may be wondering whether you should wait to sell until mortgage rates come down before you spring into action. Here’s some information that could help answer that question for you.

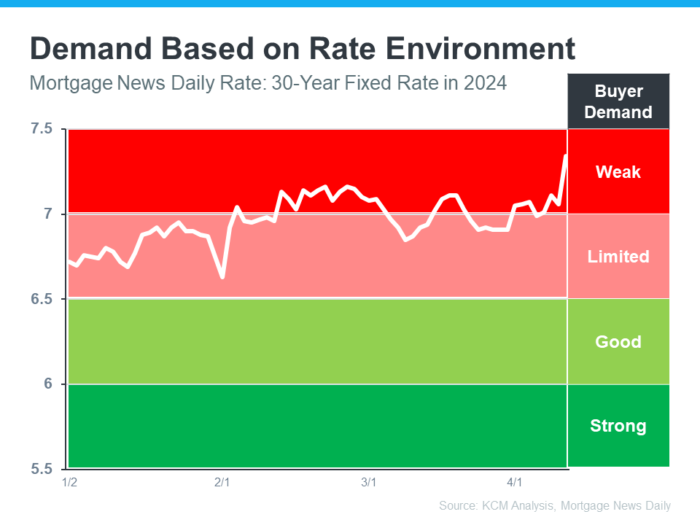
In the housing market, there’s a longstanding relationship between mortgage rates and buyer demand. Typically, the higher rates are, you’ll see lower buyer demand. That’s because some people who want to move will be hesitant to take on a higher mortgage rate for their next home. So, they decide to wait it out and put their plans on hold.

But when rates start to come down, things change. It goes from limited or weak demand to good or strong demand. That’s because a big portion of the buyers who sat on the sidelines when rates were higher are going to jump back in and make their moves happen. The graph below helps give you a visual of how this relationship works and where we are today:

As Lisa Sturtevant, Chief Economist for Bright MLS, explains:

“The higher rates we’re seeing now [are likely] going to lead more prospective buyers to sit out the market and wait for rates to come down.”

Why You Might Not Want To Wait

If you’re asking yourself: what does this mean for my move? Here’s the golden nugget. According to experts, mortgage rates are still projected to come down this year, just a bit later than they originally thought.

When rates come down, more people are going to get back into the market. And that means you’ll have a lot more competition from other buyers when you go to purchase your next home. That may make your move more stressful if you wait because greater demand could lead to an increase in multiple offer scenarios and prices rising faster.

But if you’re ready and able to sell now, it may be worth it to get ahead of that. You have the chance to move before the competition increases.

Bottom Line

If you’re thinking about whether you should wait for rates to come down before you move, don’t forget to factor in buyer demand. Once rates decline, competition will go up even more. If you want to get ahead of that and sell now, talk to a real estate agent.

Source: keepingcurrentmatters.com ~ Image: Canva Pro

How to Downsize Your Home Before a Move

Downsizing Home

How to Downsize Your Home Before a Move

Living in a large house is great for some families, but for others, the cost and effort of maintenance is a burden. This is especially true after your kids have grown up and moved out. If you’re overwhelmed in your current home, moving to a smaller space can be a great move both financially and mentally.

However, decluttering and downsizing can be a daunting task. Downsizing to a smaller home and need some help getting started? Follow our best tips for a stress-free move.

7 Most Effective Downsizing and Decluttering Tips

1. Take Inventory of Your Belongings

When you’re downsizing to a smaller home, you naturally won’t have as much space for all the items you’ve accumulated throughout the years. Before you start packing, you’ll need to take inventory of your belongings.

As you sort through everything, it’s important to separate aspirational items from the ones you actually need. If you come across something you haven’t used in the last year, you should probably get rid of it. And if you didn’t even know you still had an item in question, it’s definitely time to let it go. The purpose of downsizing is to simplify your life, so take only what you need with you.

Downsizing Tip

Start decluttering in 3 simple steps. First, set a timeline and goals for your project. Then, create a sorting system for going through your belongings. Once you’ve decided what to keep and what to part ways with, you can purge your house of the clutter. Find more expert tips on room-by-room organizing and decluttering in our ridiculously thorough home declutter guide.

Three-Box Decluttering Method With Boxes Labeled “Keep,” “Donate,” and “Store”

2. Sort Through Items Room-by-Room and Minimize Duplicates

As you go through your belongings, you’ll need to set up a system to stay organized. We recommend the Three-Box Method, which forces you to make a decision item-by-item. Gather three boxes or bins and label them as “Keep,” “Get Rid Of,” and “Put In Storage.”

You should keep items that are useful in your daily life. Once you’ve filled your “Keep” box in each room, you can pack it up and label it to make moving and unpacking easier.

Get rid of items that you no longer have a use for. Once you’ve defined the items you’re getting rid of in each room, you can sort them further by identifying what will be donated or passed down to family members, and what is worn or broken and should be thrown away.

Sentimental or seasonal items should be put in storage. After you complete each space, empty the “Put In Storage” box into neatly labeled storage containers.

Downsizing Tip

In each space, look at which items you have multiples of and only keep your favorites, or the ones that aren’t damaged. The kitchen is typically a clutter hotspot for duplicate items, so pay extra attention when decluttering this area.

3. Create a Plan to Get Rid of Unwanted Items

Once you’ve identified which items aren’t coming with you to your new home, you have several options for getting rid of them:

  • Donate or Freecycle: Give something you no longer need to someone who does. Local charities usually accept clothing, shoes, and other household items that are in good condition. You can also try posting to freecycle.org or a Facebook resale group.
  • Have a Yard Sale: One person’s trash is often another person’s treasure. If you’re downsizing a lot of your belongings before the move, consider having a yard sale to make some extra cash. Furniture, toys, books, kids’ clothes, power tools, and lawn equipment are usually popular items at a garage sale.
  • Rent a Dumpster: Chances are, not everything you’re getting rid of will be in good enough condition to donate or sell. Renting a dumpster is a stress-free option if you have a lot to downsize and declutter, or if you’re throwing away larger household items, like broken appliances or tattered furniture.
  • Pass Down to Loved Ones: It’s difficult to declutter sentimental items you no longer have use for but that hold years of memories. If there are family heirlooms in good condition that you feel a family member or friend would enjoy, offer to give them as a gift.

4. Go Digital When Possible

Over the years, paper clutter can really add up. Make time to sort through old bills, receipts, and other documents, and recycle anything you don’t need. Store older paper files, such as taxes from the last decade, in a plastic bin. Scan any other records and receipts you may need in the future so you have a digital copy, then shred and throw them away.

Home movies, music, and photos can also be converted into digital files. This will free up a lot of valuable real estate in your living room and office without having to part with things you’d otherwise keep. In the world of endless streaming services, it’s probably not worthwhile to hang onto VHS tapes, scratched DVDs, or CDs. When in doubt, throw them out (or recycle them).

5. Make the Most of Your Storage Spaces

When you’re downsizing to a smaller home, it’s important to maximize any storage space you have. While not every home has designated storage areas like a basement, attic or garage, here are some general tips to keep in mind:

  • Create built-in storage options whenever you can. Multifunctional furniture such as storage ottomans, platform beds with drawers, entertainment centers, wardrobes, bookshelves and baskets are all helpful for hiding and minimizing clutter, but traditional shelving units are always a great option too.
  • Use open wall space. Floating shelves are great for displaying knickknacks around the house, as well as adding storage in your kitchen, bedroom, and bathroom.
  • Take advantage of hidden storage spaces. Utilize extra areas in your new home, such as under the stairs, closets, and crawl spaces to store seasonal or sentimental items. Add floating shelves or cubbies, and stack clear plastic bins in these hidden spots to make the most of the space and easily find what you need. You can also get creative with adding storage to small bathrooms by adding over-the-door hooks, towel racks, standalone shelves and bins for under-counter storage, an over-the-toilet shelving unit and a medicine cabinet.

6. Measure Furniture and Wait to Buy New Things

You may not have enough room in your new, smaller home to fit all of your current furniture. While taking inventory of your belongings, measure your furniture to see if and how it will fit in your new space, or if you’ll need to part with any of it. It’s much easier to figure this out ahead of time, rather than moving a sectional couch into your new home to find it doesn’t fit.

For this same reason, you should also avoid buying new items until you get a sense of the space you’re working within the new home.

7. Give Yourself Plenty of Time

Part of figuring out how to downsize is figuring out when to downsize. Decluttering is a journey, so give yourself more time than you think you’ll need to plan for the move and downsize your belongings. Eliminate the stress of rushing to purge everything, and allow yourself to reflect and make rational decisions on what to downsize and declutter.

Finally, don’t be afraid to ask for help while downsizing. Recruit family and friends, or even hire a professional service to assist with clearing out your house and moving into your new home.

Source: budgetdumpster.com ~ By: Liz Kane ~ Image: Canva Pro

What do home inspectors look for? 6 key things

Home Inspection

When you’re under contract on a new house, it’s easy to fall in love with its potential. But before you linger on cloud nine too long, you’ll need the reality check of a home inspection. During a home inspection, a professionally trained inspector visually and physically evaluates the entire structure, from the foundation up to the roof, looking for potential defects, safety issues, environmental issues, or other red flags.

In particularly competitive markets, some buyers consider waiving the home inspection to make their offer stand out. But think very carefully before doing so: A house is most likely the largest purchase you’ll ever make. The last thing you want to do is invest a ton of money only to find out your new home needs extensive repairs or remediation. 

That’s why a home inspection is important: A good inspector can spot minor problems before they become major ones, and speak to the quality of construction and maintenance the home has been through. A home inspection helps you know as much as you can about the property before buying it, says Kenneth Carr of Precision Inspections, a licensed home inspector in New York, Connecticut, and Massachusetts. “It is part of due diligence,” Carr says. “Just as you have your attorney review the contracts, you should have your home inspector review the property, because there may be something there that you don’t have the expertise to know.”

What do home inspectors look for?

“We are looking for things that aren’t working as designed,” says Carr. “We have to describe what’s there, what may be missing, and things that are either not working as they should or not working at all, and bring it to the attention of the buyer.” Many inspectors even recommend that homebuyers attend the inspection, which allows them to see things for themselves and ask questions.

While each state provides minimum requirements that must be checked out, “how an inspector goes about inspecting the property is up to each inspector,” he says. “If you belong to an organization like ASHI [the American Society of Home Inspectors], there is greater training specialization needed, as inspectors are expected to take continuing education classes as part of their membership and state licensing.”

Here are the top six things an inspector will always look for when assessing a property.

1. Basic safety features

Whether a home is safe to live in is a primary concern for any home inspector, which is why many of the things on the home inspector’s standard checklist are safety items. Things they’re on the lookout for include:

    • Smoke detectors: Does the home have them? Are they installed correctly and in the right places (in or near sleeping areas, not too close to the stove)?
    • Ground fault interrupters: These are the special plugs that protect you from shock in areas where water and electricity are in proximity, such as bathrooms and kitchens.
    • Safety glass: Are the glass features installed near stairs or water (like tubs and showers), made of tempered safety glass?
    • Indoor and outdoor stairs: Are the steps a uniform, safe height and angle? Are they built to code? Do they have handrails and guardrails correctly installed and in the right places?

2. The foundation and exterior ‘envelope’

No matter how old the home is, your inspector will look at the basic “envelope” that shields the structure from weather and water. The inspector will walk the property to check for cracks in the foundation and look at rain gutters and flashings, drainage, and window seals.

He or she will also inspect how the walls and roof intersect. For example, an inspector doesn’t want to see lots of caulk there, because that usually means it’s not properly waterproofed. When done right, waterproofing is part of the home design — not something added after the fact. If signs of prior water penetration are found, he or she will also check whether the issue was fixed properly.

3. The roof

An inspector can tell if a roof was done properly by a professional, or sloppily by an amateur. They’ll want to make sure your roof is well constructed, isn’t showing signs of age or deterioration, and will protect you from the elements. They’ll also check to see that any openings — like a chimney or skylights — are properly sealed, flashed, and free of moss growth and debris.

The older the house, the more likely it is that the roof has already been resurfaced at least once, and roofs do need replacement from time to time, which can be an expensive process. As part of their inspection report, an inspector will typically provide an estimate of how many good years the roof has left before you should consider replacing it.

4. Major systems: electrical, plumbing, etc.

The inspector will check out all of your home’s most important interior systems, from electrical and plumbing to heating and air conditioning.

    • Heating and air: How well does the heating and cooling work? Do they serve every area in the home evenly? Is there good airflow in every room? If there’s an air return, is it properly located and sized to serve the house efficiently?
    • Plumbing: The inspector will check to see that the plumbing is in good shape, provides enough water to the house, and drains as it should — no one wants leaky pipes letting water into their home and causing flooding or mold problems. He or she will also ensure there is sufficient water flow and pressure. If the house uses well water, ask to have the pump and water quality checked.
    • Electrical: Electricity is essential for modern life, but it can also be dangerous. An inspector will make sure that your electrical system is safe, provides enough power for the house, and is installed and grounded correctly. They’ll also check to make sure there are enough outlets and look at the electrical panel — an old or obsolete panel may become a fire hazard. 

5. Ventilation

Dangerous fumes can build up in a house if appliances that run on oil or natural gas, like water heaters for example, aren’t installed and configured the right way. Proper ventilation is crucial. Many of these appliances have safety features built-in, but an inspector will make sure the safety equipment is correctly enabled.

Besides checking the water heater’s ventilation, the inspector will also check its maximum temperature to make sure your tap water can’t get hot enough to burn anyone. Additionally, he or she will make sure that clothes dryers are properly vented to catch lint and expel hot air, which helps prevent house fires and may also test for radon.

6. Signs a specialist is needed

Some areas or conditions might need further examination, often by a specific type of pro with specialized equipment. A good inspector will know when to call in the heavy hitters, and may even have a network of specialists they can refer you to.

For example, a fireplace is one feature that always gets careful evaluation. The inspector wants to see that it vents well and doesn’t have any conditions that could become a hazard, like cracks, blockages, or excessive buildup. If they see something concerning, your inspector might recommend a fireplace inspector, who will use a specialized camera to scope out the interior of the chimney and flue.

Sewers are another area that calls for extra care, especially in an older house. A septic problem hidden beneath your yard can be one of the most expensive repairs a homeowner must make. If you’re buying a home that has sewer service, consider calling in a specialist to have the whole system (from the main house to the street) video scoped or a video inspection that goes through pipes, holes, and other areas.

Source: bankrate.com ~ By: Dori Zinn & Grace Kim ~ Image: Canva Pro

How to buy a house in 2024

Buying home in 2024

Last year may go down in real estate history as the year of correction. After a pandemic-fueled, seller-benefitting boom — with bidding wars, inventory shortages, and spiraling prices all over the country — the housing market began to cool down in 2022. The impact of inflation and fast-rising interest rates dampened buyers’ interest, causing sales to slow and price appreciation to decelerate.

All this made 2023 something of a transitional year. And now, in 2024, inflation is much lower but home prices and mortgage rates are both still high. Sellers still have an edge in many areas, thanks to a continued scarcity of houses, and no one expects a dramatic housing market crash. Still, many analysts see a shift coming toward a more balanced market, which would benefit buyers.

Whatever the economic state of the real estate market, buying a house can be an exciting and emotional process. Before starting your search, be sure you understand the ins and outs of homebuying, so you can make the best decisions for your family — and your wallet. Here’s what to know when buying a house, one step at a time.

Buying a house: A step-by-step guide

1. Determine why you want to buy a house

Purchasing a home is a major decision that shouldn’t be taken lightly. If you’re not clear on exactly what you want out of homeownership, you could end up regretting your choice.

Get started: Define your personal and financial goals. “Buyers should think about when they intend on moving and what they want in a home — amenities, ideal location, and how long it could take them to save for a down payment,” says Edwence Georges, a real estate agent with RE/MAX in Westfield, New Jersey. “These are all important to help define the goals they would like to meet.”

    • Make a list of what’s important to you in a home. Is location the top priority? Any must-have amenities?
    • Analyze whether it makes sense for you financially. Would renting for another year or two improve your financial standing?
    • Be sure you’re prepared for the ongoing expenses of maintaining a home.

2. Check your credit score

Your credit score will help you determine your financing options; lenders use it (among other factors) to set the terms and rates of your loan. The higher your score, the lower the interest rate you will be eligible for — lower scores equate to more expensive mortgages.

Get started: You can get your credit report and score from each of the three major credit reporting agencies, Equifax, Experian, and TransUnion, for free once a year. Your bank or credit card company might offer free access to your score or credit report, too. If you discover any discrepancies, contact each agency and report the error.

    • Consider how different credit score ranges impact your interest rate, monthly payments, and total interest.
    • Pull your credit reports from each of the credit bureaus for free every 12 months at AnnualCreditReport.com.
    • Learn other ways to get your free credit report and score.

3. Save for a down payment

To avoid having to pay private mortgage insurance or PMI, you’ll need to put down at least 20 percent of the home’s purchase price for a down payment. Some lenders offer mortgages without PMI with lower down payments but expect to pay a higher interest rate. Be sure to do your research: Many types of loans require a much lower minimum down payment, and there are many government programs to help cover down payment costs for qualified buyers. Shop around carefully based on how much you’re able to pay upfront.

Get started: Research the requirements for the loan you want so you know exactly how much you’ll need to save for a down payment. If a friend, relative, or employer has offered to provide a down payment gift, initiate a conversation early on to learn how much they plan to contribute and if there’s any shortfall you’ll need to cover — and secure a gift letter from them well in advance.

    • Consider options backed by the federal government. If you qualify for an FHA, VA or USDA loan, your down payment minimum will be considerably lower than 20 percent.
    • Conventional loans offered by Fannie Mae and Freddie Mac, meanwhile, require just 3 percent down.
    • Look into local and state down payment assistance programs to see if you’re eligible for a cost-saving loan or grant.

4. Create a housing budget

The purchase price and down payment aren’t the whole picture. Setting a realistic budget for your new home will help inform how much you can afford and what your all-in costs will be.

Get started: Carefully consider other expenses to determine what you can afford long-term. “Buyers tend to forget to factor in other costs, like homeowners association fees and maintenance,” says Paige Kruger, Realtor and founder of Signal Real Estate in Jacksonville Beach, Florida. “Just because you can afford a mortgage and a down payment doesn’t mean you can afford those long-term costs after you move.”

    • Figure out how much you can set aside for a down payment, plus a buffer fund for ongoing or unexpected maintenance costs.
    • Determine the maximum loan you qualify for. Getting pre-approved can help (see Step 5).
    • Analyze your monthly budget to make sure you can handle mortgage payments along with your other day-to-day bills.

5. Shop for a mortgage

Getting pre-approved for a mortgage gives you a firmer handle on how much you can afford, and it’s helpful when you make an offer on a house because it shows sellers you’re financially qualified. Once you’re ready to apply for official approval, you’re not obligated to stick with the same lender that issued your preapproval — compare the terms and rates offered by several companies.

Get started: Shop around with at least three lenders or a mortgage broker to increase your chances of getting a low-interest rate. Sign up for a Bankrate account to determine the right time to strike on your mortgage with our daily rate trends.

    • Work with an experienced mortgage lender who can walk you through all the options and overall costs.
    • If you’re a first-time homebuyer, inquire about what programs or incentives might be available to you.

6. Hire a real estate agent

An experienced real estate agent can save you time and money by helping you find the right home and negotiating with the seller on your behalf. Agents are licensed professionals who know their markets well and can guide you through your homebuying journey.

Get started: Contact several local real estate agents and talk with them about your needs before choosing one. “Someone with knowledge of an area can tell if your budget is realistic or not, depending on the features you desire in a home,” Kruger says. “They can also point you to adjacent areas in your desired neighborhood or other types of considerations to help you find a house.”

    • Before hiring an agent, ask about their track record and knowledge of your desired neighborhood.
    • Inquire about their workload as well. You don’t want someone who is over-scheduled.
    • Bankrate can help match you with a qualified agent in your area.

7. Go house-hunting

Viewing listing photos online is helpful, but isn’t a substitute for visiting homes in person and getting to know the area and its amenities. In some cases, the right neighborhood might be even more important than the home itself.

Get started: Be specific with your agent about exactly what kinds of homes you want to see, so they can more effectively find options that meet your criteria. Keep an open mind: You may not be able to check off everything on your wish list, so prioritize must-haves over things that are nice to have but not crucial.

    • Explore neighborhoods you like to see what’s for sale, and attend open houses for homes that pique your interest.
    • Take notes on each property you visit — after a few, they can start to blend together in your mind.
    • Keep your schedule open so you can pounce when a great home is listed, especially in a competitive market.

8. Make an offer

Understanding how to make an attractive offer on a home can help increase the chance of it being accepted, putting you one step closer to getting those coveted keys. Confer with your agent and let their expertise lead the way.

Get started: Once you find “the one,” your real estate agent will help you prepare a complete offer package, including your offer price, your preapproval letter, proof of funds for a down payment (this helps in competitive markets), and terms or contingencies.

    • Think carefully about what contingency clauses to include in your contract. Common real estate contingencies can hinge on financing, appraisal, home inspection, and more.
    • It’s not unusual for sellers to make a counteroffer. You can respond if you wish to keep negotiating, or reject it and move on.
    • Once an offer is accepted, you’ll sign a purchase agreement and pay an earnest money deposit, typically 1 to 2 percent of the purchase price. The funds will be held in escrow until closing.

9. Get a home inspection

A home inspection provides an overall picture of the property’s condition and any mechanical or structural issues it might have. This will help you determine how to proceed with the closing process: If major problems are found, you might want to ask the seller for repairs — or, if there’s an inspection contingency in the contract, you might even decide to back out of the deal.

Get started: Your agent can probably recommend a home inspector, but do your homework before choosing one. Depending on your contract and what state you’re in, you’ll generally need to complete the inspection within 10 to 14 days of signing a purchase agreement.

    • Check the inspector’s experience by reading online reviews, asking for client references, and looking at their credentials.
    • To understand what is and isn’t covered, read Bankrate’s home inspection checklist.
    • Fees can vary, but according to HomeAdvisor, you’ll likely pay somewhere between $281 and $403. The average is $342.

10. Negotiate repairs and credits

Your home inspection may reveal a few issues, especially if it’s an older home. Major problems might need to be dealt with before your mortgage lender will finalize your loan, and it’s common to negotiate for the seller to either pay for the repair or offer the buyer a credit to cover the cost.

Get started: Enlist your agent’s help with this — the need for repairs is not unusual, but negotiation can be delicate work and is best left to the pros. They will work with the seller’s agent to come to an agreement about repairs or credits.

    • Hazardous problems like structural damage or improper electrical wiring could keep your lender from approving your loan, so take the solutions very seriously.
    • Some sellers won’t agree to extensive repairs. That’s why a home inspection contingency is important — it gives you a way out of the deal if you need it.

11. Secure your financing

A preapproval is not the same thing as official approval. Getting final loan approval means you need to keep your finances and credit in line during the underwriting phase. Don’t open new credit lines or make any major purchases until the paperwork is signed, and avoid changing jobs before closing too, if possible.

Get started: Respond promptly to requests or questions from the lender, and double-check your loan estimate to ensure all the details are correct. You may need to submit additional paperwork as your lender completes the process, such as bank statements, tax returns or additional proof of income, so keep your paperwork organized.

    • Being preapproved doesn’t mean you’re in the clear — that’s not the case until a lender has given your loan the final stamp of approval.
    • Keep your finances and credit in good shape from preapproval until closing day.
    • Avoid running up credit cards, taking out new loans or closing credit accounts too. These things can hurt your credit score or impact your debt-to-income ratio, which can imperil your final loan approval.

12. Do a final walk-through

A final walk-through is your opportunity to view the property one last time before it becomes yours. This is your last chance to address any outstanding issues before the house becomes your responsibility.

Get started: Your agent will schedule the walk-through for shortly before closing. Bring your home inspection checklist and other documents, like repair invoices and receipts, to ensure everything was done as agreed and that the home is move-in ready.

    • Ask your agent to attend with you — they can act as a witness and help answer any questions.
    • If any problems remain, have your agent communicate immediately with the seller and your lender. Your closing date might have to be delayed to ensure those issues are remedied first.

13. Close on your house

Once all contingencies have been met, you’re happy with the final walk-through and your lender has declared your loan “clear to close,” it’s finally time to make it official and close on your new home. After all of the paperwork has been signed, the home is officially yours and you’ll get the keys. Congratulations!

Get started: Three business days before your closing date, the lender will provide you with a closing disclosure that outlines your loan details, such as the monthly payment, loan type and term, interest rate, loan fees and how much money you must bring to closing. You will attend the closing along with your real estate agent, possibly the seller and their agent, and the closing agent, who may be a representative from the escrow or title company or a real estate attorney. This is also when you’ll wire your closing costs and down payment, depending on the escrow company’s procedures.

    • When you get your closing disclosure, compare it to your loan estimate to ensure the terms are the same. Ask any questions and correct any errors before you sign the paperwork.
    • On closing day, review all the documents you sign carefully, and ask for clarification on anything you don’t understand.
    • Make sure you’re given all house keys, entry codes, and garage door openers before leaving the closing.

Other things to consider

Is it the right time to buy?

Traditionally, spring is the start of the homebuying season, with many listings hitting the market and activity peaking over late spring/early summer. However, your own financial readiness is more important than the time of year.

Mortgage rates recently hit highs not seen in more than 20 years. Meanwhile, strong demand for homes has pushed prices higher and frustrated many potential homebuyers. This combination of high rates and high prices has plenty of people wondering whether they should try to buy a home now, or wait for things to settle down.

The answer likely depends on your own personal circumstances more than the condition of the housing market. If you’re financially stable, you have enough in savings to cover the down payment and other expenses, your employment and income are secure, and you’re ready to stay in one place for a while, then now is a perfectly fine time to buy a house. You can always refinance if rates drop significantly. On the other hand, if your savings are tight or your credit score is less than stellar, it might make more sense to take time to build those before buying.

One thing to keep in mind: Be sure to exercise caution anytime there’s a spike in home prices. “Be careful about buying near the top of the market, especially if you want to be in the home for only a few years,” says Ken H. Johnson, a real estate economist at Florida Atlantic University and co-author of the Beracha, Hardin & Johnson Buy vs. Rent Index. If you’re looking to buy under these conditions, says Johnson, “bargain aggressively and be willing to walk away.”

What’s your local market like?

The area you’re house-hunting in has a major impact on what to brace for as a homebuyer. Each market has its own quirks to consider: For example, the taxes, cost of living, job market and housing situation in California will yield different buying conditions than in Texas or Ohio. And even within the same city, real estate is very localized — you might be surprised by how drastically market conditions can vary from one neighborhood to the next. This is why partnering with a knowledgeable local agent who understands the intricacies of their market is so important.

How prepared are you for extra costs?

The down payment is often considered the biggest homebuying expense, since it’s a large amount that the buyer has to actually pay upfront. But homeownership involves plenty of additional costs that you should be ready for. Before you even close on the purchase, you’ll need to make sure you have enough money set aside to cover closing costs. These fees will vary by state and by individual transaction, but they will almost certainly range into the thousands of dollars.

When budgeting for your monthly housing costs, factor in not only the principal and interest amounts of your mortgage payment, but also property taxes, home insurance premiums, and homeowners association fees (if applicable), plus private mortgage insurance if you’re putting down less than 20 percent. And don’t forget to set aside money for ongoing maintenance and unexpected repairs, too.

Source: bankrate.com ~ By: Jeff Ostrowski ~ Image: Canva Pro

Is Reprieve in Mortgage Rates Enough to Move Buyers?

Mortgage Interate Rates

Mortgage rates are starting to cool off after nearly hitting 7% in recent weeks. Borrowing costs have eased somewhat and housing affordability is showing signs of improvement—just in time for the spring selling season.

The 30-year fixed-rate mortgage averaged 6.74% this week, Freddie Mac reports. Over the last two weeks, rates have fallen by nearly a quarter of a percentage point. Potential home buyers are responding: Mortgage applications for a home purchase—a gauge of future homebuying activity—rose by 5% in the latest week and have been increasing over the last two weeks as rates have moved lower, the Mortgage Bankers Association reports.

For home buyers looking to purchase a $400,000 home with a 20% down payment, the estimated monthly mortgage payment at this week’s rate equates to about $2,073, says Jessica Lautz, deputy chief economist at the National Association of REALTORS®. Compared to October, when rates surged to a 7.79% average, home buyers can now save about $228 per month, she says.

Mortgage rates in the mid-6% range are encouraging more home buyers to return to the market. “Homebuying activity is showing an increase in buyer demand from last year when buyers were apprehensive of rising rates,” Lautz says. But “more housing inventory is needed to meet the demand.” House hunters are still facing multiple-offer situations as they scramble to compete for low inventory.

Home buyers will continue to watch rates carefully, as they also continue to face record-high home prices. While economists have largely predicted rates to stay in the 6.5% or 6.3% range for most of 2024, week-to-week fluctuations remain a wild card for the housing market. Plus, “despite the recent dip, mortgage rates remain high as the market contends with the pressure of sticky inflation,” says Sam Khater, Freddie Mac’s chief economist. “In this environment, there is a good possibility that rates will stay higher for a longer period of time.”

Freddie Mac reports the following national averages with mortgage rates for the week ending March 14:

  • 30-year fixed-rate mortgages: averaged 6.74%, dropping from last week’s 6.88% average. Last year at this time, 30-year rates averaged 6.6%.
  • 15-year fixed-rate mortgages: averaged 6.16%, falling from a 6.22% average last week. A year ago, 15-year rates averaged 5.9%.

Source: nar.realtor ~ By: Melissa Dittmann Tracey ~ Image: Canva Pro

Skip to content